The Account No One Wanted to Open
The Account No One Wanted to Open
Part 1 – The Man in the Rain
At 3:17 on a rainy Thursday afternoon, Riverside Bank was busier than usual.
Water streamed down the large glass windows facing Main Street. Wet umbrellas leaned against chairs. Customers stood in a long line beneath warm ceiling lights while printers hummed, keyboards clicked, and quiet conversations blended with the steady sound of rain.
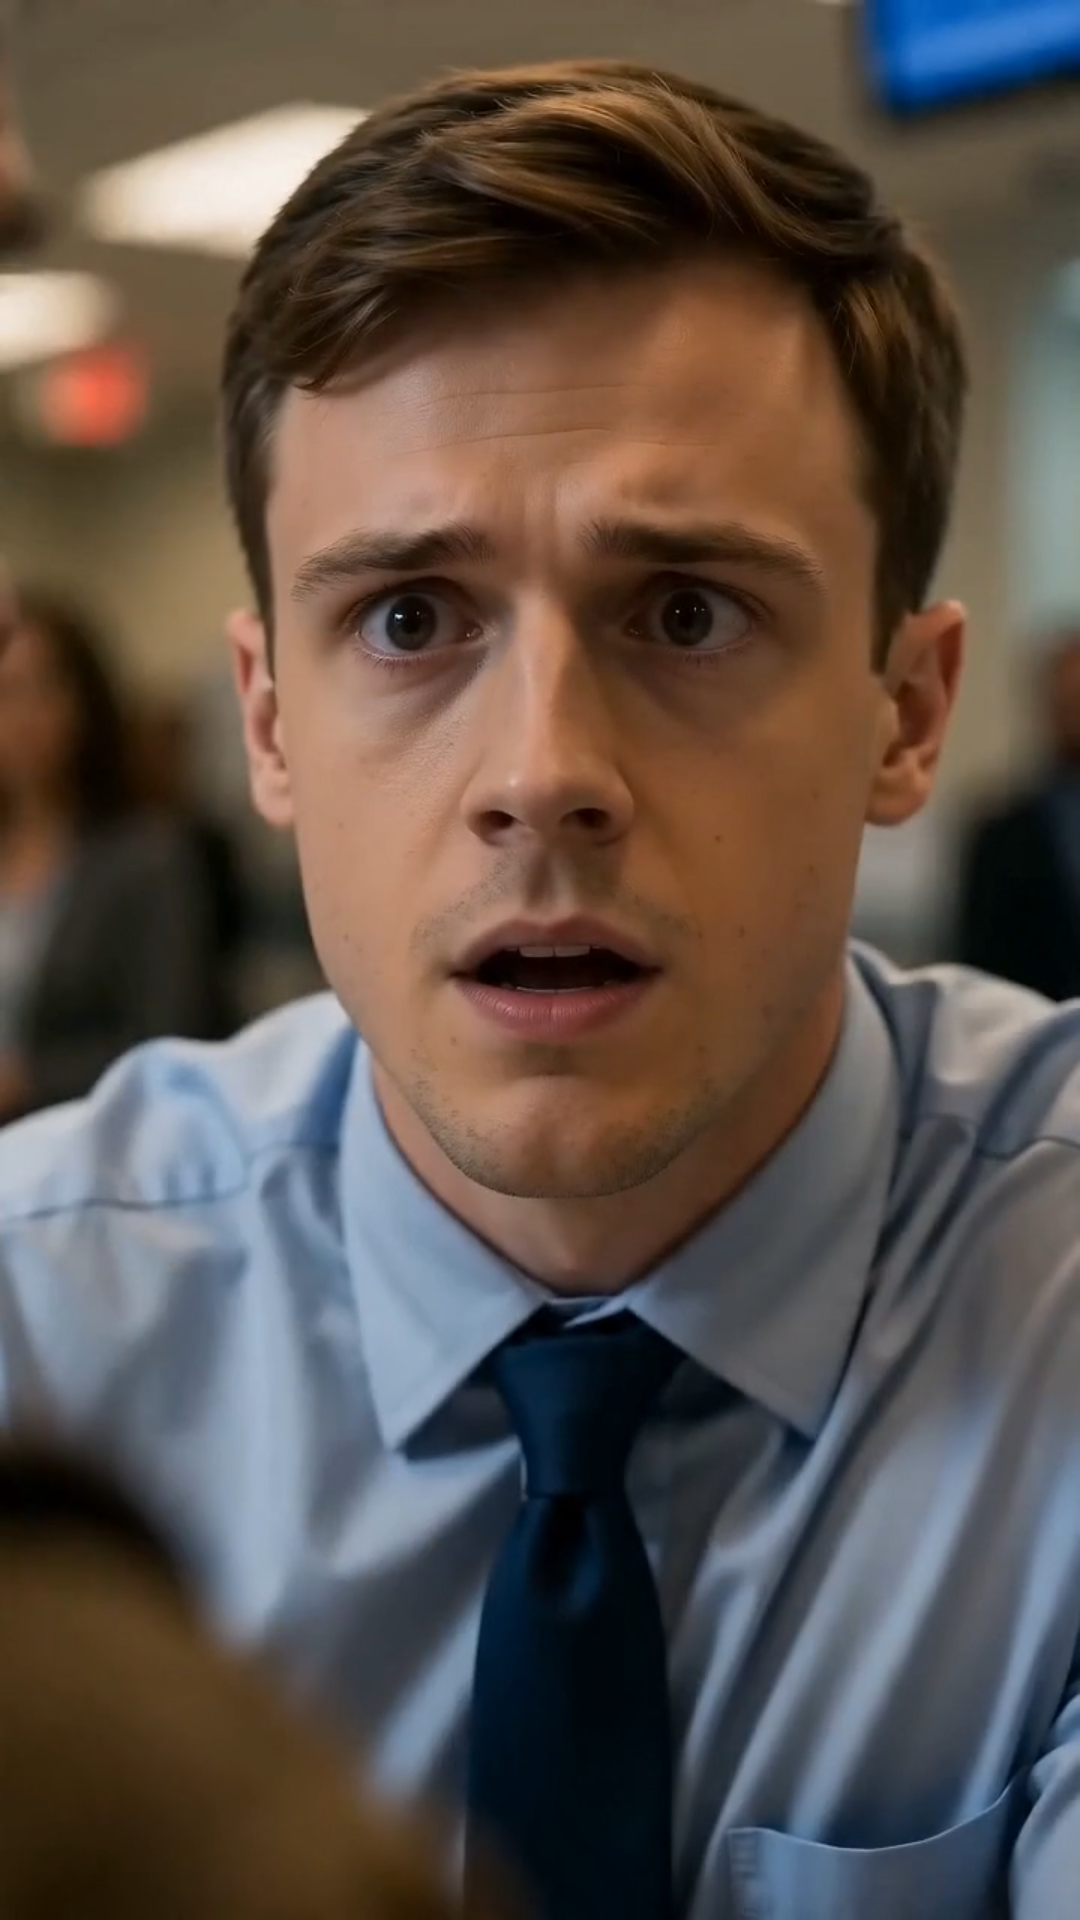
At the third service counter, twenty-four-year-old Daniel Brooks helped an elderly woman reset her online banking password.
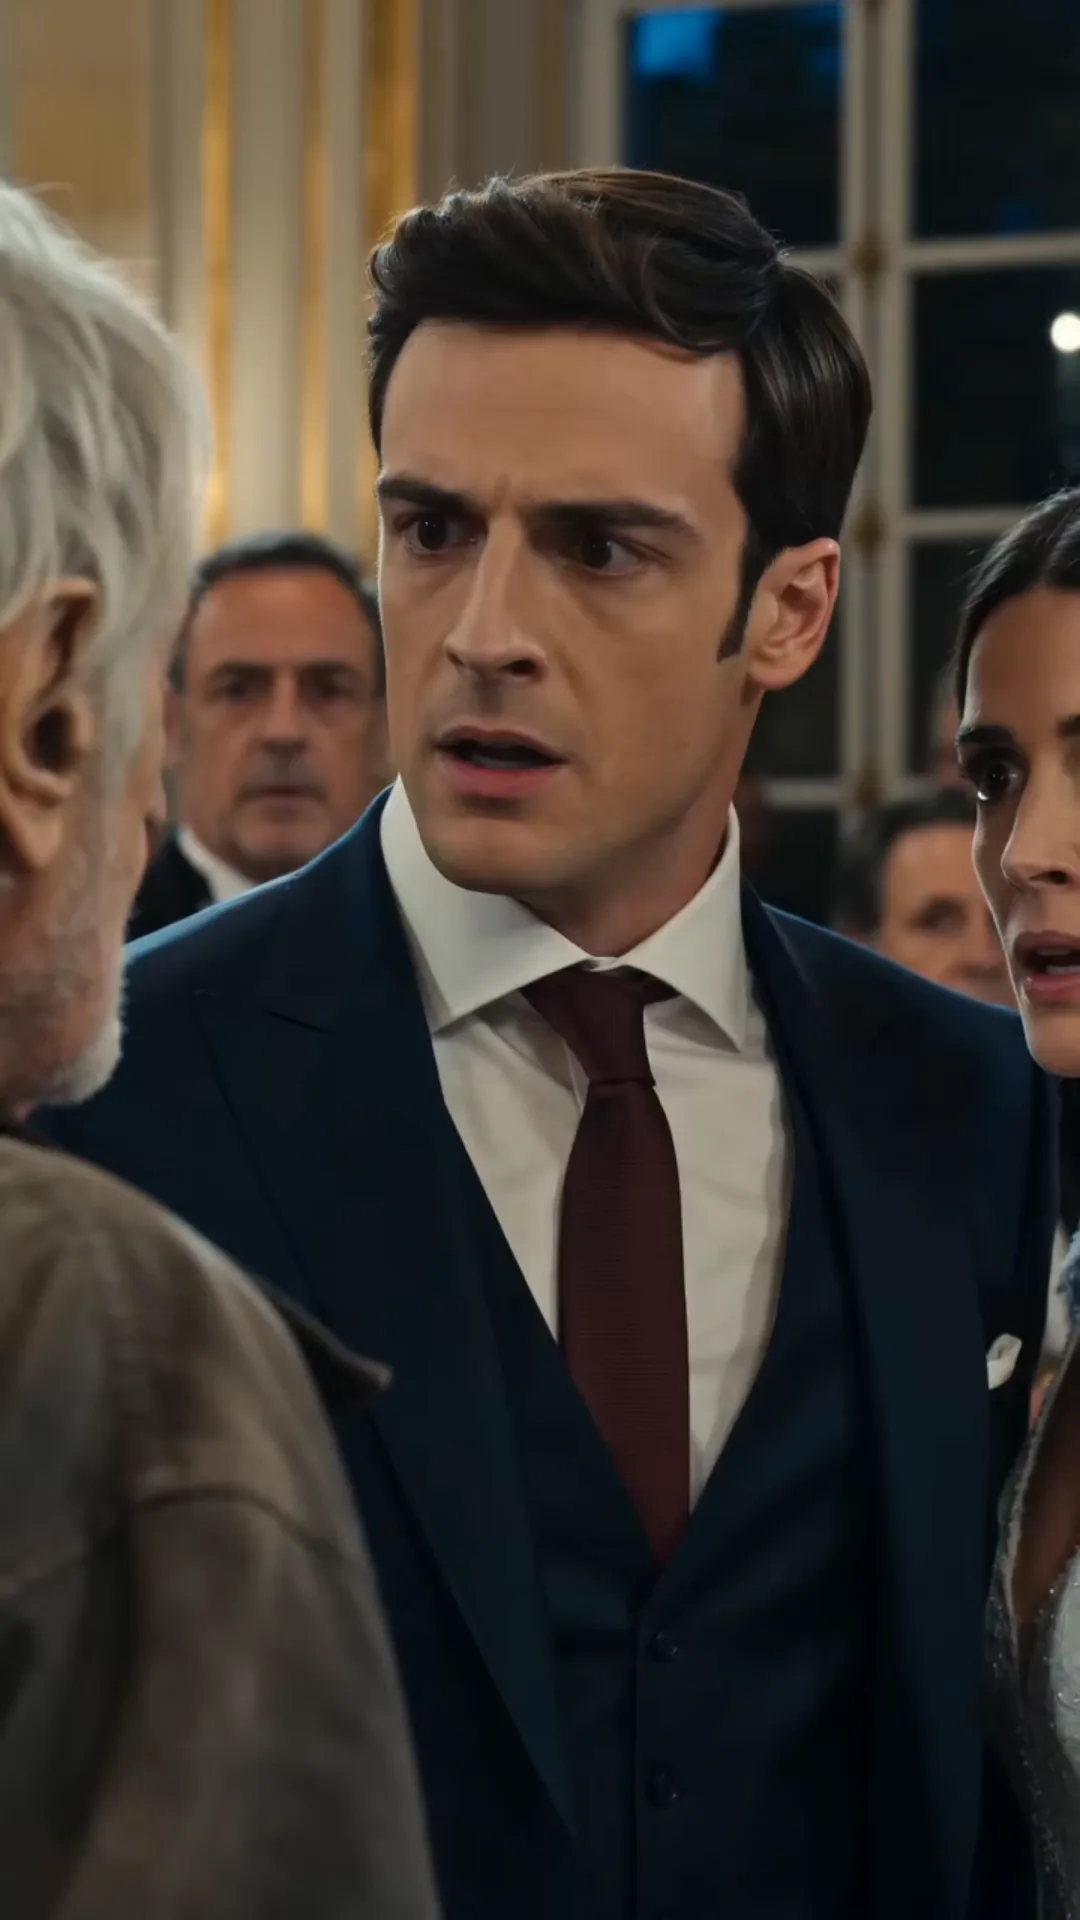
Daniel wore a light-blue shirt, a navy tie, charcoal pants, and black shoes polished that morning before work. His short brown hair was neatly combed, though a few strands had fallen across his forehead after six hours behind the counter.
“Try writing the new password somewhere safe,” he told the woman.
She smiled.
“My daughter says I should remember everything.”
“Daughters say many ambitious things.”
The woman laughed.
Daniel handed back her identification.
“There you go, Mrs. Campbell. You’re all set.”
“Thank you for being patient with me.”
“That’s what I’m here for.”
As she left, Daniel glanced toward the clock.
His lunch break had been postponed twice.
He had not complained.
Daniel needed the job.
His father had died when Daniel was seventeen, leaving behind medical debt and an unfinished mortgage. Daniel’s mother worked mornings in a school cafeteria, but arthritis had recently made it difficult for her to stand.
Daniel covered most of the household expenses.
He also sent money to his younger sister, Emily, who was studying to become a teacher.
Every paycheck had already been divided before it reached his account.
Rent.
Electricity.
Medication.
Tuition.
Gas.
Groceries.
Daniel had once dreamed of becoming a financial counselor for low-income families. He wanted to help people understand credit, savings, and debt before a single emergency destroyed years of work.
But dreams required time.
Bills did not wait.
For now, he was a teller at Riverside Bank, earning enough to keep his family stable and hoping someone in management might eventually notice his ability.
Someone had noticed him.
Unfortunately, it was Branch Manager Charles Whitmore.
Charles was fifty-two, tall, silver-haired, and always dressed in a dark suit. He believed appearance created trust, and trust created profit.
He measured employees by speed, sales targets, and how many premium accounts they opened each month.
Daniel was good with customers.
Charles did not consider that enough.
“You spent twelve minutes helping that woman,” Charles said as he passed Daniel’s counter.
“She couldn’t access her account.”
“She has six hundred dollars in savings.”
Daniel looked at him.
“Does that change her password?”
Charles lowered his voice.
“Your job is not to become everyone’s personal assistant.”
“My job is to help customers.”
“Your job is to understand which customers are worth your time.”
Before Daniel could answer, the bank’s glass doors opened.
Cold air and rain blew into the lobby.
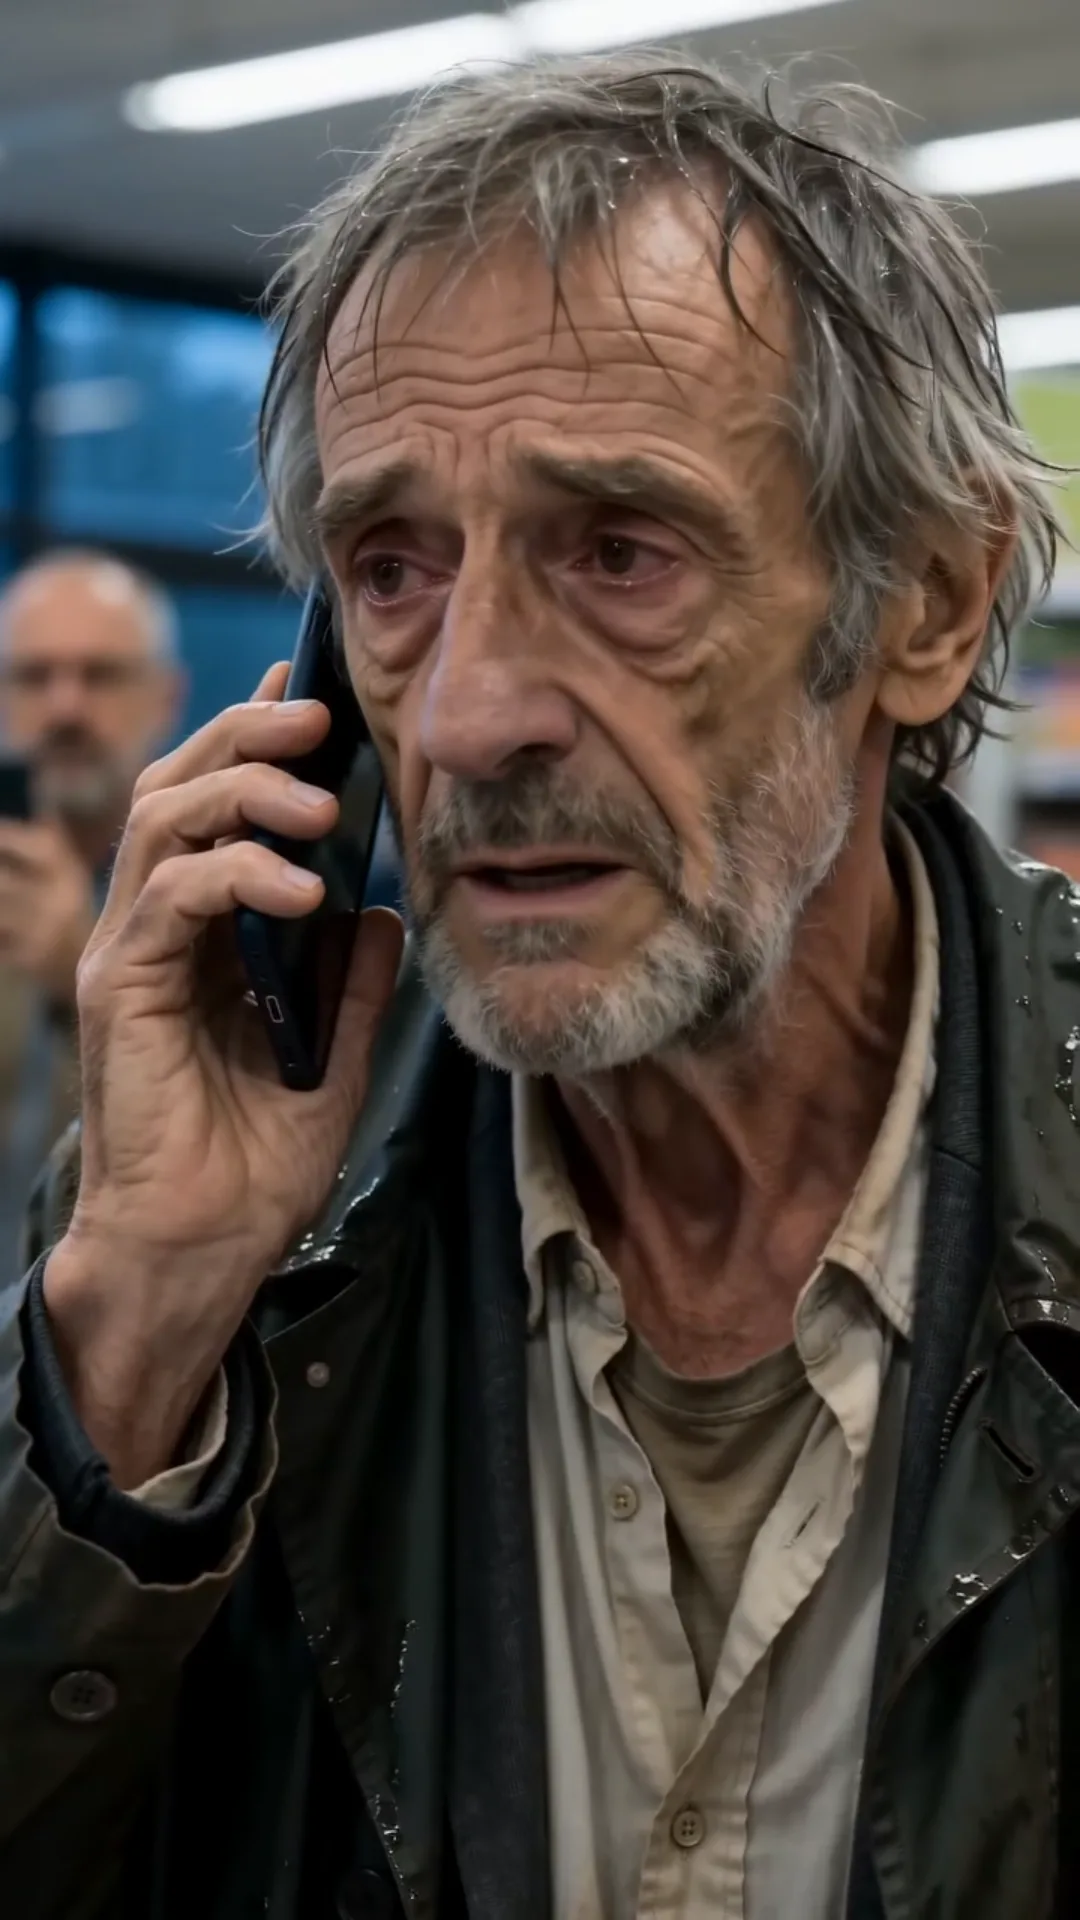
A thin older man stepped inside.
He was soaked.
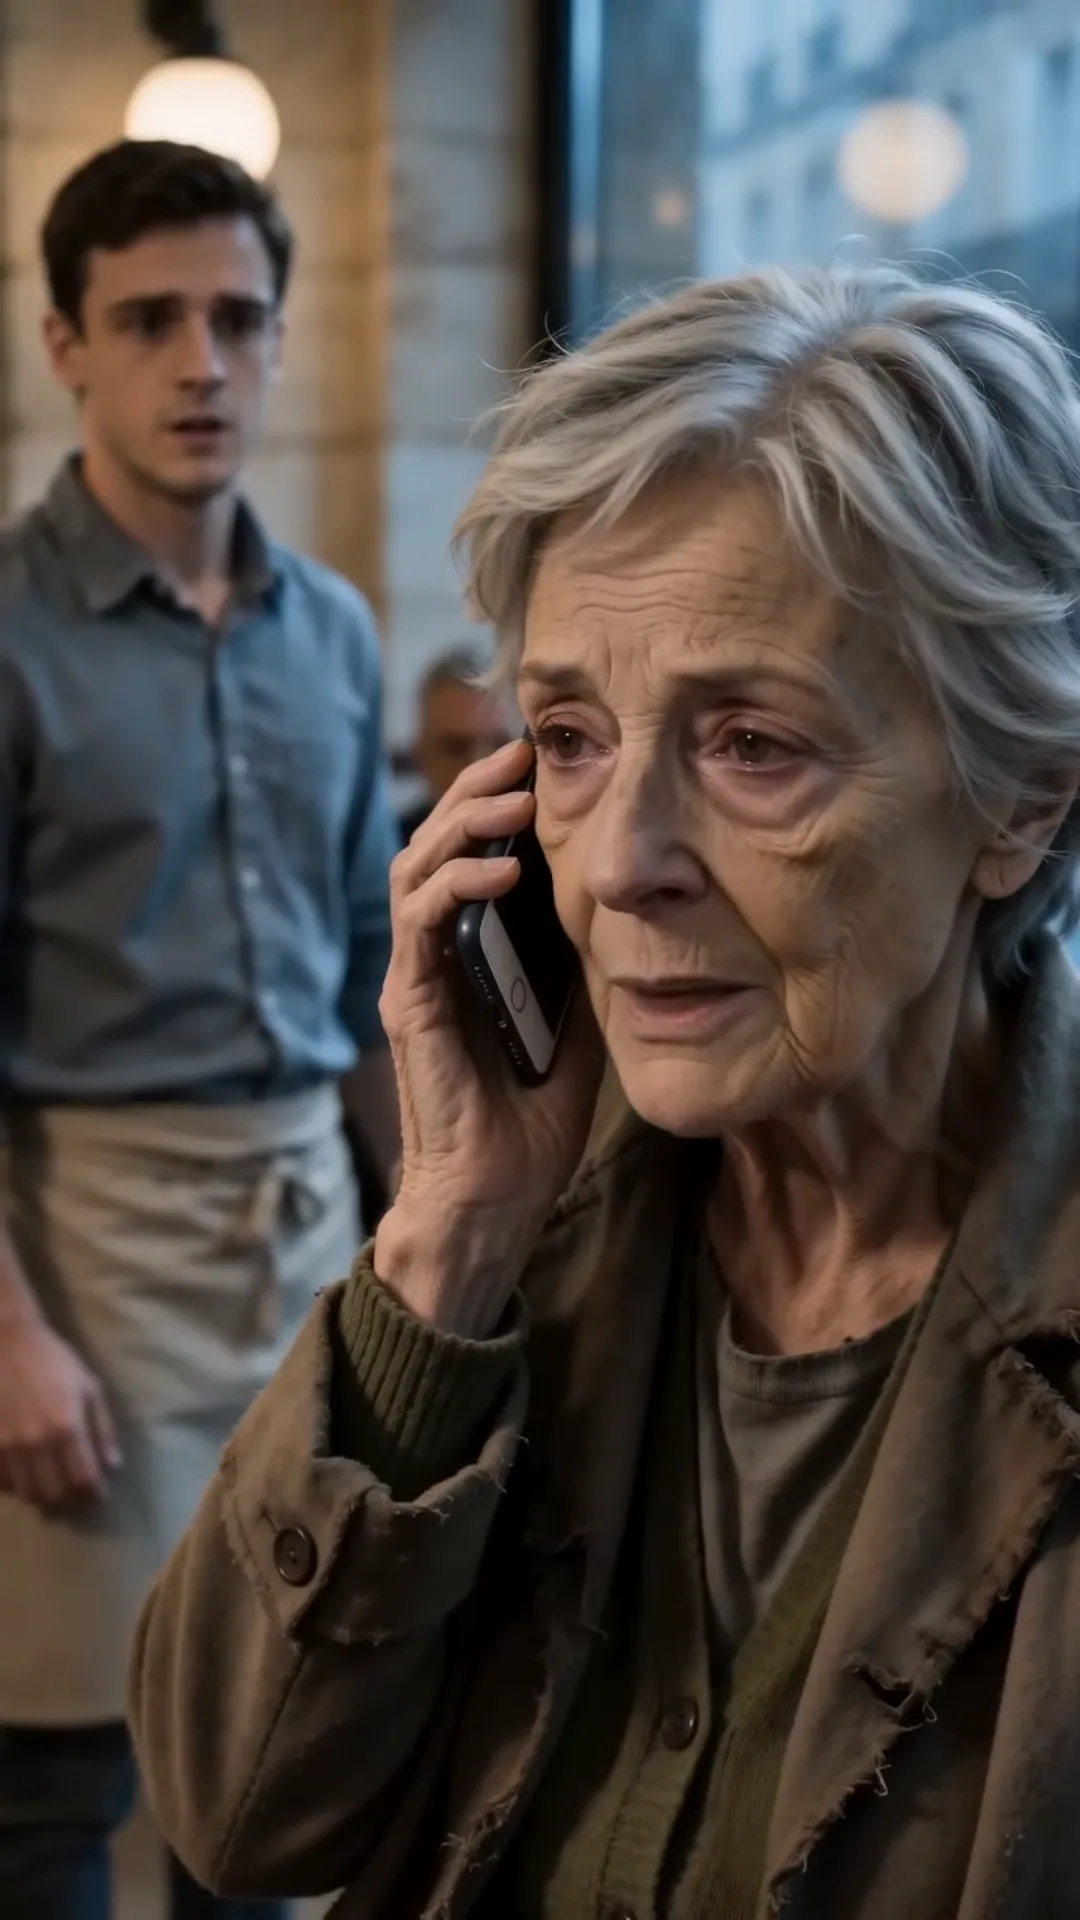
His gray hair clung to his forehead. A short beard covered his jaw. He wore a brown coat darkened by rain, worn jeans, and boots with cracked leather near the toes.
An old backpack hung from one shoulder.
Several customers turned to look at him.
A woman near the deposit table pulled her handbag closer.
A security guard straightened near the entrance.
The man removed his faded cap and held it against his chest.
Water dripped from his sleeves onto the polished floor.
“Can I help you?” the security guard asked.
The question did not sound welcoming.
The man looked toward the service counters.
“I’d like to open a bank account.”
A customer in line glanced at his clothes and smirked.
The guard hesitated.
“Do you have an appointment?”
“No.”
“Identification?”
“Yes.”
“An opening deposit?”
The man looked down.
“I have some cash.”
“How much?”
The question was loud enough for nearby customers to hear.
The old man’s face tightened.
“I’d rather discuss that privately.”
Charles Whitmore had been watching from across the lobby.
He approached.
“We are very busy today,” he said. “There is a check-cashing store two blocks east.”
The old man looked at him.
“I didn’t ask to cash a check.”
“I understand. But they may be better equipped to serve your needs.”
Daniel heard the conversation.
He stepped away from his counter.
“I can help him.”
Charles turned.
“You have customers waiting.”
“So does everyone else.”
The next woman in Daniel’s line shook her head.
“I don’t mind waiting.”
Charles ignored her.
He looked back at the old man.
“Sir, perhaps you should return when you have the required documentation.”
The man opened his backpack.
The security guard immediately moved one hand toward his belt.
The man froze.
“I’m only getting my identification.”
Daniel saw fear in his face.
He walked around the counter.
“It’s okay,” Daniel said. “Take your time.”
The man slowly removed an old envelope.
Inside was a state identification card, a Social Security card, and several folded documents protected in a plastic bag.
Daniel accepted them carefully.
“Mr. Henry Carter?”
The old man nodded.
“Yes.”
“My name is Daniel. I can help you open an account.”
Charles stepped closer.
“Daniel.”
Daniel looked at him.
“This is not an appropriate use of your time.”
Henry lowered his eyes.
“I can leave.”
Daniel shook his head.
“You came here to open an account.”
Charles spoke quietly but sharply.
“He doesn’t belong here.”
The lobby fell silent enough for several customers to hear.
Daniel stared at his manager.
“Everyone deserves respect.”
Charles’s face hardened.
“You are speaking to your manager.”
“And he is speaking to a customer.”
Henry looked between them.
“I don’t want anyone losing a job because of me.”
Daniel offered him a chair near the side desk.
“Please sit down.”
Henry hesitated, then followed.
His boots left wet footprints across the floor.
Daniel brought him a towel from the employee break room and a paper cup of water.
“Would you like coffee?”
Henry shook his head.
“Water is fine.”
Daniel sat across from him.
“What kind of account are you looking for?”
“A basic checking account.”
“Do you receive income through direct deposit?”
Henry smiled faintly.
“Not anymore.”
“Retirement benefits?”
“A small monthly payment.”
“That can be deposited automatically.”
Henry nodded.
“I’ve been keeping everything in cash.”
“May I ask why?”
“I didn’t trust banks.”
Charles, standing nearby, gave Daniel an impatient look.
Daniel ignored him.
“What changed your mind?”
Henry’s fingers tightened around the water cup.
“A man at the shelter stole money from my backpack last week.”
Daniel glanced at the old bag beside his chair.
“I’m sorry.”
“It wasn’t much.”
“It was yours.”
Henry looked at him for a moment.
“Yes.”
Daniel opened the application.
“Do you have a permanent address?”
Henry looked toward the rain-covered windows.
“No.”
Daniel paused.
Charles folded his arms as though the problem had proved his point.
Riverside Bank required a mailing address, but federal guidelines allowed customers without permanent housing to use the address of a shelter, relative, or approved service organization.
Daniel knew that because he had read the compliance handbook.
Most employees had not.
“Do you stay at a shelter?” Daniel asked.
“Sometimes.”
“Would they allow you to receive mail there?”
“I think so.”
“Then we can use that address with verification.”
Henry’s eyes lifted.
“You can?”
“Yes.”
Charles interrupted.
“This application will require additional review.”
“That’s fine,” Daniel replied.
“It will delay the entire account-opening process.”
Daniel looked at Henry.
“Are you in a hurry?”
Henry smiled for the first time.
“No.”
“Then neither am I.”
They continued.
Daniel explained minimum balances, ATM fees, debit card protection, and direct deposit.
He avoided technical language.
He did not speak louder than necessary.
He did not treat Henry like a child.
When they reached the opening deposit, Henry took a small cloth pouch from his backpack.
Inside were folded bills.
One-dollar bills.
Fives.
Tens.
A few twenties.
He placed them carefully on the desk.
“One hundred and forty-three dollars,” he said.
Charles glanced at the amount and walked away in disgust.
Daniel counted it twice.
“Would you like to deposit all of it?”
Henry kept three dollars.
“For the bus.”
Daniel nodded.
“That’s a good idea.”
Henry signed the final page slowly.
His hand trembled slightly.
When he finished, Daniel placed the documents in a folder.
“Your account is open.”
Henry looked at the folder.
“That’s it?”
“That’s it.”
“No one is going to close it because I don’t have a house?”
“No.”
“No one can take the money without permission?”
“Not legally.”
Henry released a quiet breath.
“Thank you.”
Daniel handed him a temporary debit card.
Henry held it carefully.
“It has my name on it.”
“Yes.”
Henry stared at the card as though it were evidence that he still existed.
Charles approached.
“Daniel, come to my office.”
Daniel looked at Henry.
“Will you be okay getting to the bus stop?”
“I’ll be fine.”
Daniel stood.
Charles did not wait for him.
Inside the glass-walled office, he closed the door.
“You openly challenged me in front of customers.”
“I helped someone open an account.”
“You embarrassed this branch.”
“By following banking regulations?”
“By suggesting I was disrespectful.”
Daniel looked through the glass.
Henry stood near the lobby entrance, placing his folder into the old backpack.
“You said he didn’t belong here.”
“He did not fit our target customer profile.”
“He had valid identification and an opening deposit.”
“He will never qualify for a mortgage, investment account, or premium credit product.”
“So?”
Charles stared at him.
“This bank is a business, not a shelter.”
Daniel’s jaw tightened.
“He didn’t ask for shelter. He asked for an account.”
“You have been warned repeatedly about ignoring performance priorities.”
“You mean I spend too much time with people who aren’t rich.”
“I mean you lack judgment.”
Daniel laughed once in disbelief.
Charles opened a drawer and removed a termination form.
“Turn in your badge.”
Daniel stopped smiling.
“You’re firing me?”
“For insubordination and failure to follow management direction.”
“My mother depends on my insurance.”
“That is not the bank’s responsibility.”
The words struck Daniel harder than he expected.
He thought of his mother’s medication.
His sister’s tuition payment due next week.
The mortgage notice in the kitchen drawer.
He could apologize.
He could say he had misunderstood.
He could promise to improve.
Charles pushed the form toward him.
Daniel looked through the glass again.
Henry was still near the door.
Several customers were watching.
Daniel slowly removed his badge.
He placed it on the desk.
“I’d do it again.”
Charles took the badge.
“You can collect your personal belongings.”
Daniel left the office.
Henry immediately understood.
“He fired you.”
Daniel picked up his coat from behind the counter.
“It’s okay.”
“No, it isn’t.”
“I’ll find something else.”
Henry looked toward Charles.
“Because you helped me?”
“Because I challenged him.”
“You challenged him because of me.”
Daniel placed his belongings into a small cardboard box.
“You did nothing wrong.”
Henry stepped closer.
“What will happen to your family?”
Daniel paused.
“How do you know I have a family?”
“You wear worry like a wedding ring.”
Daniel almost smiled.
“I’ll manage.”
Henry reached inside his soaked coat.
Daniel assumed he was searching for bus fare.
Instead, Henry removed a slim, expensive smartphone.
The screen lit beneath his trembling fingers.
Several customers noticed.
Charles emerged from his office.
Henry made a call.
A woman answered immediately.
Henry’s posture changed.
His shoulders straightened.
His voice became calm and authoritative.
“Prepare the acquisition.”
Charles stopped walking.
Henry listened.
“Yes,” he said. “Move the final review forward.”
He turned toward the glass windows.
“I’m at Riverside Bank.”
The entire lobby fell silent.
Henry ended the call.
Daniel stared at him.
“What acquisition?”
Henry looked at Charles.
“The one your board has been negotiating for seven months.”
Charles’s face lost its color.
Henry continued.
“My name is Henry Carter.”
A customer whispered.
The name moved through the room.
Henry Carter was the founder of Carter Financial Group, one of the largest private banking and investment companies in the country.
He had disappeared from public life years earlier after the death of his wife.
Business magazines still estimated his wealth in the billions.
Charles shook his head.
“That’s not possible.”
Henry glanced at his soaked coat.
“Which part troubles you? The money or the clothes?”
Outside, two black vehicles pulled to the curb.
Executives stepped into the rain.
Henry looked at Daniel.
“I came here to find out how this bank treats people when it believes they have nothing.”
He turned to Charles.
“Now I know.”
Part 2 – The Test
Within minutes, the bank lobby changed.
Two attorneys entered carrying leather cases.
A physician checked Henry’s blood pressure.
An assistant brought him a dry coat.
A woman named Laura Stanton introduced herself as chief operating officer of Carter Financial Group.
Customers remained in the lobby, pretending not to listen.
Charles Whitmore stood near his office.
His confidence had disappeared.
Daniel still held the cardboard box containing his coffee mug, a family photograph, and two pens.
Henry pointed toward the badge on Charles’s desk.
“Give it back.”
Charles swallowed.
“Mr. Carter, I believe we should discuss this privately.”
“You fired him publicly.”
Charles looked at Daniel.
“He violated a direct instruction.”
Henry nodded.
“Yes. The instruction was discriminatory.”
“I was protecting the bank from compliance risk.”
Laura opened a file.
“Mr. Brooks followed federal customer-identification guidance correctly. A recognized shelter address is acceptable with verification.”
Charles’s mouth tightened.
“He still ignored management authority.”
Henry looked at Daniel.
“Why did you?”
Daniel hesitated.
“Because Mr. Carter had the right documents.”
“That’s not the whole answer.”
Daniel glanced around the room.
“Because everyone was looking at him like he was dangerous.”
Henry waited.
Daniel continued.
“And because I know what it feels like when someone decides your value before hearing you speak.”
Henry studied him.
“Explain.”
Daniel looked down at the box.
“My father died owing money to this bank.”
Charles stiffened.
Daniel continued.
“Our mortgage fell behind. My mother came here to ask for more time. A loan officer told her people like us should not buy houses they couldn’t afford.”
Henry’s expression changed.
“How old were you?”
“Seventeen.”
“Did the bank foreclose?”
“Almost. My mother worked two jobs. We caught up.”
“And you chose to work here?”
“I thought I could help people from inside.”
Charles spoke.
“He was hired as a teller, not a social worker.”
Henry turned toward him.
“That distinction may explain why this branch is failing.”
Charles blinked.
“Our branch is profitable.”
“Your transaction volume is declining. Customer retention is below regional average. Employee turnover has doubled.”
Charles stared at Laura.
She closed the file.
“We reviewed the records before today.”
Henry continued.
“I did not walk in here randomly.”
Daniel looked at him.
“This was a test?”
“Yes.”
Henry sat in one of the lobby chairs.
“Carter Financial Group is considering purchasing Riverside Bank’s parent company. I wanted to observe several branches without an entourage.”
“So you dressed as a homeless man?” Daniel asked.
Henry looked at his wet coat.
“These clothes belong to me.”
Daniel frowned.
Henry continued.
“For the last three months, I have spent several nights each week in shelters.”
The room became quiet again.
“Why?” Daniel asked.
“Because my wife spent the last years of her life building financial programs for people without permanent housing.”
Henry’s voice softened.
“After she died, I discovered I knew almost nothing about the people she served.”
He looked at the temporary debit card in his hand.
“I had spent decades building banks, but I did not know how difficult it could be to open a basic account without an address.”
Laura lowered her eyes.
Henry continued.
“So I decided to learn.”
Charles gave a nervous laugh.
“Surely there were safer ways.”
“Safer for whom?”
Charles said nothing.
Henry looked at Daniel.
“In four branches, I was turned away before reaching a desk.”
Daniel’s face tightened.
“In two branches, security followed me.”
Henry nodded.
“At one, they threatened to call police because I asked to use the restroom.”
A woman waiting in line covered her mouth.
“Here,” Henry continued, “one employee treated me like a customer.”
He held up the debit card.
“This piece of plastic is ordinary to most people. To someone who has been locked outside the financial system, it can mean safety, employment, and dignity.”
Daniel looked at the card.
Henry turned to Charles.
“You did not merely insult me. You demonstrated a culture.”
Charles straightened.
“I have worked for Riverside for twenty-three years.”
“Then you have had twenty-three years to learn better.”
Henry looked toward Laura.
“Has the board accepted our offer?”
“They are ready for final authorization.”
Henry nodded.
“Approve it.”
Laura stepped aside to make the call.
Charles looked at Daniel.
“I can reinstate you immediately.”
Daniel said nothing.
Charles continued.
“There was clearly a misunderstanding.”
Henry’s expression hardened.
“You understood everything perfectly until you learned my net worth.”
Charles’s face reddened.
“That is unfair.”
“No,” Daniel said quietly. “It’s accurate.”
Charles turned toward him.
“You need this job.”
Daniel looked at the cardboard box.
He did.
His mother’s medication would run out in twelve days.
His sister’s tuition payment was due Friday.
He had less than nine hundred dollars in savings.
Fear pressed against his chest.
But he remembered Henry sitting at the desk, holding a debit card with his name on it.
Daniel set the box down.
“I’ll come back under one condition.”
Charles looked relieved.
“What condition?”
“You don’t decide whether I come back.”
Charles stared at him.
Daniel turned to Henry.
“I want to know what changes.”
Henry nodded slowly.
“What would you change?”
Daniel had thought about that question for years.
“Basic accounts with no minimum balance.”
Laura, still on the phone, looked toward him.
“Financial counseling that doesn’t begin with a sales pitch.”
Henry nodded.
“What else?”
“Partnerships with shelters so people can verify addresses.”
“Reasonable.”
“Small emergency loans that don’t trap people in fees.”
Charles interrupted.
“That would create risk.”
Daniel looked at him.
“People are already taking risks. They’re borrowing from payday lenders at impossible rates.”
Henry’s eyes sharpened with interest.
Daniel continued.
“Teach people how credit works before they need it. Help teenagers open savings accounts. Stop charging customers for being poor.”
Charles scoffed.
“That is not how banking works.”
Henry smiled faintly.
“Perhaps that is why banking needs to change.”
Laura ended the call.
“The acquisition is approved.”
The words settled across the lobby.
Riverside Bank had a new owner.
Henry stood.
“Mr. Brooks, I am offering you your position back with full back pay.”
Daniel nodded.
“Thank you.”
“And I want you on a branch reform committee.”
Daniel blinked.
“I’m a teller.”
“You are also the only person here who understood the problem without needing a billionaire to explain it.”
Charles looked furious.
“You cannot place a junior employee over branch leadership.”
Henry turned toward him.
“Mr. Whitmore, you are suspended pending a conduct review.”
Charles’s face went pale.
“You said earlier that this is a business, not a shelter.”
Henry stepped closer.
“You were right about one thing. It is a business.”
His voice remained calm.
“And businesses fail when they confuse cruelty with discipline.”
Security did not remove Charles.
Henry did not humiliate him.
He simply asked him to leave the building.
Charles walked through the lobby carrying nothing.
No one recorded him.
Daniel watched him go.
He expected to feel satisfied.
Instead, he felt tired.
Henry noticed.
“You wanted him fired?”
“No.”
“You defended him?”
“No.”
“Then what troubles you?”
Daniel looked toward the rain.
“I know what it feels like to lose a job when people depend on you.”
Henry studied him.
“Compassion after being mistreated is expensive.”
Daniel looked at him.
“So is becoming the person who mistreated you.”
Henry nodded.
Before leaving, Henry handed Daniel a business card.
“My direct number.”
Daniel looked at it.
“You carry business cards in that coat?”
“I carry many things in that coat.”
Daniel almost laughed.
Henry lowered his voice.
“There is one more reason I came today.”
“What?”
Henry’s expression changed.
“The shelter where I have been staying is about to close.”
Daniel frowned.
“Why?”
“The building was sold.”
“To whom?”
Henry looked toward Laura.
“A development company owned indirectly by Carter Financial.”
Daniel stared at him.
“You’re closing the shelter?”
“I learned about it three days ago.”
“But it’s your company.”
“That does not mean I know every decision made beneath my name.”
Daniel’s disappointment was visible.
Henry accepted it.
“You wanted to know why I was really here.”
He looked at the temporary bank card again.
“I came to discover whether my institutions still served people.”
“And?”
Henry’s eyes filled with regret.
“I discovered they had become very good at serving my balance sheet.”
Part 3 – The Run on Riverside
The following weeks transformed Riverside Bank.
Carter Financial announced a pilot program called Open Door Banking.
Customers could open basic checking accounts without minimum balances or overdraft penalties.
Local shelters were approved as mailing addresses.
Employees received training on homelessness, disability, trauma, and financial exclusion.
A small counseling office opened beside the lobby.
There were no sales quotas inside it.
Daniel was asked to help design the program.
He spent mornings at the teller counter and afternoons meeting with compliance officers, nonprofit leaders, and software teams.
At first, they treated him like a symbolic employee invited for good publicity.
Daniel quickly changed that.
He challenged confusing forms.
He pointed out hidden fees.
He insisted the mobile app work on older phones.
He asked why identification rules were explained only in legal language.
During one meeting, an executive said, “People should take responsibility for understanding their finances.”
Daniel replied, “Then we should take responsibility for making the information understandable.”
Henry smiled from the end of the table.
The shelter threatened with closure was given a two-year lease extension.
Henry ordered an investigation into the sale.
He learned that a senior development executive had hidden the shelter’s role in the community by listing the building as “underperforming commercial property.”
The executive was dismissed.
Henry took responsibility publicly.
“No institution becomes unfair in one dramatic moment,” he told reporters. “It becomes unfair through thousands of decisions no one important bothers to examine.”
The interview went viral.
So did the story of Daniel and the account Henry had opened with one hundred and forty dollars.
Public reaction was mixed.
Many praised the changes.
Others called them reckless.
Financial commentators warned that no-fee accounts would lose money.
Competitors accused Henry of turning banking into charity.
Charles Whitmore appeared on a local television program.
He claimed he had been sacrificed for publicity.
“I followed established procedures,” he said. “Mr. Carter staged an emotional test and punished me for refusing to abandon professional standards.”
Daniel watched the interview from the bank break room.
Several employees looked at him.
One asked, “Do you think he believes that?”
Daniel turned off the screen.
“Yes.”
Henry entered the room using a cane.
His health had visibly worsened.
The assistant accompanying him tried to hide concern.
Daniel noticed.
“You okay?”
Henry sat.
“I am seventy percent functional before coffee.”
“You look like thirty percent.”
“Then bring coffee.”
Daniel handed him water instead.
Henry frowned.
“My doctor has corrupted you.”
“Your doctor didn’t need help.”
Henry drank.
Daniel sat across from him.
“Charles is telling people we destroyed his career.”
“We did not.”
“We suspended him, investigated him, and made him famous for the worst thing he said in public.”
Henry looked at him.
“Do you think he should return?”
Daniel took a long breath.
“I think if Open Door Banking is supposed to help people change, we should believe employees can change too.”
Henry leaned back.
“You want me to offer him a job?”
“Not his old one.”
“What kind?”
“Customer hardship review.”
Henry laughed.
“You want the man who rejected struggling customers to review hardship cases?”
“With supervision.”
“That sounds either wise or insane.”
“Probably both.”
Henry studied him.
“Why?”
“Because policies feel different when you meet the people trapped inside them.”
Henry looked toward the lobby.
“That lesson changed you?”
“No. It changed you.”
Henry smiled.
Charles refused the first offer.
He called it insulting.
Two weeks later, he returned.
His wife had been diagnosed with breast cancer.
Without the bank’s insurance, their treatment options were limited.
Charles entered Daniel’s office looking smaller than before.
“I need work.”
Daniel did not remind him of the day he had said a family’s medical needs were not the bank’s responsibility.
He gave Charles the job description.
“You’ll begin as a case assistant.”
Charles read it.
“The salary is half what I earned.”
“Yes.”
“You would supervise me?”
“Yes.”
Charles looked at him.
“You’re enjoying this.”
Daniel answered honestly.
“No.”
Charles searched his face.
That seemed to trouble him more.
He accepted the position.
For several months, the program grew.
More than twelve thousand people opened basic accounts.
Shelter residents received direct deposits safely.
Workers without traditional addresses were able to cash paychecks without losing large percentages to fees.
Teenagers opened savings accounts through school partnerships.
Then a rumor began online.
A false post claimed Riverside Bank was near collapse because of “free accounts” and risky loans.
The post spread rapidly.
Customers started withdrawing money.
By noon on Friday, lines wrapped around the block.
News trucks arrived.
The bank’s app slowed under heavy traffic.
Executives urged Henry to suspend Open Door Banking and reassure premium customers first.
He refused.
“Every customer receives the same information.”
A board member raised his voice.
“We may face a liquidity crisis.”
Henry looked toward Daniel.
“What do customers need?”
“Facts,” Daniel said. “And someone they trust.”
Henry nodded.
“You speak.”
Daniel stared at him.
“To the press?”
“To everyone.”
“I’m not an executive.”
“That may be why they believe you.”
Daniel stepped outside beneath the bank awning.
Rain fell lightly.
Hundreds of customers waited behind metal barriers.
Cameras turned toward him.
His hands shook.
Charles stood nearby.
“You don’t have to do this,” Charles said.
Daniel looked at the crowd.
“Yes, I do.”
He approached the microphones.
“My name is Daniel Brooks. I work at Riverside Bank.”
A reporter shouted.
“Is the bank insolvent?”
“No.”
“Why are customers unable to access the app?”
“Too many people are logging in at once. The system is being expanded.”
“Are deposits safe?”
“Yes. Insured deposits remain protected under federal law.”
Another reporter called out.
“Did your no-fee program cause this?”
“No.”
“How can you be sure?”
“Because the bank’s financial records do not support that claim.”
A woman near the front shouted.
“My retirement money is in there!”
Daniel looked directly at her.
“You have every right to withdraw it.”
The executives watching from inside stiffened.
Daniel continued.
“But before you decide, please speak with one of our counselors. We will show you the numbers. We will not pressure you to stay.”
The crowd quieted slightly.
“We built Open Door Banking because fear becomes expensive when people have nowhere trustworthy to ask questions.”
He looked toward the cameras.
“We are not going to respond to fear by hiding information or treating wealthy customers better than everyone else.”
For three hours, employees met customers one by one.
Charles sat with an elderly veteran who wanted to empty his account.
He explained insurance protections patiently.
The man chose to withdraw only enough for one month.
At another desk, Daniel helped a single mother access funds for rent when the app failed.
Henry remained in the lobby despite his doctor’s objections.
By evening, withdrawals slowed.
Then Laura entered carrying a report.
“We found the source.”
Henry looked up.
The rumor had originated from a consulting firm hired by a competitor seeking to weaken Riverside before a regional expansion.
Evidence was sent to regulators and law enforcement.
The crisis ended.
But Henry collapsed before he could hear the full report.
Daniel caught him near the customer service desk.
“Henry?”
Henry’s face was gray.
He gripped Daniel’s sleeve.
“My chest.”
Someone called an ambulance.
Employees cleared the lobby.
Charles knelt beside him and loosened his tie.
Henry looked at him.
“You came back.”
Charles nodded.
“I’m trying.”
Henry closed his eyes.
At the hospital, doctors discovered severe heart complications worsened by untreated stress.
Surgery was required.
Henry refused to sign the consent form until Daniel arrived.
“You’re being ridiculous,” Daniel said.
Henry lay beneath white hospital sheets, suddenly looking much older than sixty-eight.
“Possibly.”
“Sign it.”
“I need you to promise me something.”
Daniel crossed his arms.
“No dramatic final speeches.”
“Very well. A practical final speech.”
“You’re not dying.”
“That is the preferred outcome.”
Henry looked toward the window.
“If I do not recover, the board may cancel Open Door Banking.”
Daniel’s expression tightened.
“Can they?”
“They will call it financially inefficient.”
“What do you want me to do?”
Henry reached into the bedside drawer and removed a folder.
Inside was a proposal establishing the Carter Community Banking Trust.
It would fund Open Door Banking independently for twenty years.
Daniel stared at it.
“You already solved the problem.”
“Not entirely.”
Henry pointed to the final page.
It required the signature of the trust’s first executive director.
Daniel saw his own name.
“No.”
Henry sighed.
“You reject opportunities with impressive consistency.”
“I am not qualified to run this.”
“You helped build it.”
“I’m twenty-four.”
“That condition improves automatically.”
Daniel almost smiled.
Henry continued.
“Banks have enough people who understand money. They need more people who understand what money does to those who do not have it.”
Daniel looked at the signature line.
“What if I fail?”
“You will.”
Daniel stared at him.
Henry smiled weakly.
“Then you will correct the failure and continue.”
Daniel signed.
Henry entered surgery an hour later.
The operation lasted through the night.
Outside, rain began falling again over Riverside Bank.
Inside the hospital waiting room, Daniel sat beside Charles.
For a long time, neither spoke.
Then Charles said, “The day I fired you, I told myself I was protecting the bank.”
Daniel looked at him.
“I know.”
“I wasn’t.”
“No.”
“I was protecting my authority.”
Daniel nodded.
Charles looked down at his hands.
“My wife starts treatment Monday.”
“How is she?”
“Terrified.”
“So are you.”
Charles’s eyes filled.
“Yes.”
Daniel handed him a cup of coffee.
Charles accepted it.
“I don’t deserve your help.”
Daniel looked toward the surgery doors.
“Most people need help before they deserve it.”
Part 4 – A Place at the Counter
Henry survived the surgery.
Recovery was slow.
For several weeks, he could walk only with assistance.
He hated the physical therapist.
The physical therapist appeared to enjoy this.
Daniel visited twice a week.
He brought reports from the bank, customer letters, and terrible vending-machine coffee.
Three months later, Henry returned to Riverside Bank.
Employees gathered in the lobby.
There were no cameras.
Henry had requested none.
Daniel stood near the same desk where the first account had been opened.
The original temporary debit card had been framed.
Beneath it was a small plaque:
Account 000001 — Open Door Banking
Henry looked at it.
“You framed my card?”
“Charles did.”
Henry turned.
Charles stood near the counseling office.
His dark suit had been replaced by a simple blue shirt and striped tie.
He looked nervous.
Henry approached him.
“How is your wife?”
“Treatment is working.”
“I’m glad.”
Charles nodded.
“So am I.”
Henry looked toward the office.
“How many hardship cases have you reviewed?”
“Four hundred and twelve.”
“How many approved?”
“Three hundred and six.”
“Too generous?”
Charles looked at Daniel.
“He asks me that every week.”
Daniel smiled.
Charles continued.
“I used to believe rules protected the bank from people.”
Henry waited.
“Now I think good rules protect people from the bank.”
Henry extended his hand.
Charles shook it.
No apology could erase the past.
But change did not require erasing it.
It required remembering accurately.
The Carter Community Banking Trust opened offices in twelve cities.
Daniel became executive director while continuing part-time work with customers.
He refused a corner office.
He preferred a small room beside the lobby.
Years passed.
Open Door Banking served hundreds of thousands of people.
The program proved profitable, though not in the way traditional bankers expected.
Customers who began with ten dollars later opened business accounts.
Teenagers who learned to save returned for mortgages.
People trusted the bank because the bank had trusted them first.
Daniel completed graduate studies in public finance.
His mother retired.
Emily became a teacher.
The Brooks family paid off their mortgage.
Daniel kept the final payment receipt in his desk.
Henry lived another fourteen years.
He spent much of that time visiting shelters, schools, and community banks without announcing his arrival.
He stopped pretending to be homeless.
He no longer needed the disguise.
By then, employees had learned that every person entering the lobby belonged there.
When Henry died at eighty-two, his funeral was held in a small church.
Bank executives attended.
So did shelter residents, teachers, veterans, cashiers, bus drivers, and families who had once been denied accounts elsewhere.
Daniel delivered the final remarks.
“Henry Carter was known as a billionaire,” he said. “But the most important account he ever opened contained one hundred and forty dollars.”
Soft laughter moved through the room.
“He spent his life believing wealth gave him authority. In his final years, he learned that wealth gave him responsibility.”
Daniel looked toward Henry’s empty chair.
“He did not save Riverside Bank alone. He walked into it needing help.”
Years later, on another rainy afternoon, Riverside Bank was crowded.
The lobby looked warmer than it had on the day Henry first entered.
A sign near the door read:
No permanent address? Ask us about your options.
Daniel, now forty-one, stood near the customer counseling desk.
He had begun to show gray near his temples.
A young teller named Marcus was helping customers at counter three.
The glass doors opened.
A woman entered wearing a wet hotel uniform.
She carried a sleeping child and two plastic bags.
Customers turned briefly, then returned to their business.
The woman approached Marcus.
“I need to open an account.”
Marcus smiled.
“Of course.”
She shifted the child against her shoulder.
“I don’t have an address.”
“That’s okay. Are you staying somewhere that can receive mail?”
“A family shelter.”
“We work with several. Which one?”
The woman gave him the name.
Marcus offered her a chair.
Daniel watched from across the lobby.
The branch manager walked past.
“Do you need assistance?” she asked.
Marcus shook his head.
“I’ve got it.”
The woman removed a handful of bills from her pocket.
“Is twenty-seven dollars enough?”
“There’s no minimum deposit.”
She looked confused.
“No minimum?”
“No.”
Marcus began explaining the account.
Slowly.
Clearly.
Without looking at the growing line.
A customer behind the woman checked his watch.
Then he noticed the sleeping child.
He said nothing.
Daniel walked toward the framed temporary debit card on the wall.
Charles, now retired, had sent flowers that morning for the anniversary of Open Door Banking.
Beside the frame sat Henry’s old backpack.
Inside it remained the cloth pouch, the faded cap, and the documents protected in plastic.
Daniel touched the worn fabric.
A college intern stood nearby.
“Did Mr. Carter really come in looking homeless?”
“He came in looking like himself.”
The intern frowned.
“What does that mean?”
Daniel looked toward Marcus and the woman opening her first account.
“It means the rest of us needed to learn how to see him.”
At the desk, Marcus handed the woman a temporary debit card.
Her name was printed across the front.
She stared at it.
“This is mine?”
“Yes.”
“No one can take the money?”
“Not without your permission.”
The same questions.
The same relief.
The woman began to cry.
Marcus looked worried.
“Did I do something wrong?”
She shook her head.
“No.”
She held the card tightly.
“No one has put my name on anything in a long time.”
Daniel felt Henry’s presence in the room.
Not as a billionaire.
Not as an owner.
As an older man soaked from the rain, asking for one place where his money—and his dignity—might be safe.
The woman placed the card inside her wallet.
“Thank you.”
Marcus smiled.
“That’s what we’re here for.”
Outside, rain moved across the glass windows.
Inside, printers hummed and keyboards clicked.
The line continued.
No one was asked whether they looked profitable.
May you like
No one was told they belonged somewhere else.
And the account no one had wanted to open became the reason thousands of doors remained open for everyone who came after.